Working out the landed cost of an imported vehicle is only half of the picture. Most buyers in Sri Lanka finance part of the price through a bank, a finance company or a leasing company, and the choices you make on the loan can change what you pay by millions of rupees. This guide takes one real-world landed cost and shows, with exact figures, how the down payment, the term and the interest rate affect the total.
First: how much can you borrow?
Since 25 May 2026, the Central Bank of Sri Lanka limits vehicle financing (CBSL Act Directions No. 01 of 2026). For motor cars, SUVs, vans and three-wheelers that are unregistered, or registered in Sri Lanka for less than one year, a bank, finance company or leasing company may lend at most 40% of the vehicle’s value. The cap covers finance leases, hire purchase, vehicle loans and any other credit for buying a vehicle.
For a newly imported car, that means a down payment of at least 60%. (Vehicles registered in Sri Lanka for more than one year can be financed up to 60%.) Letters of credit opened before 25 May 2026 may qualify for the earlier, higher limits under the Direction’s transitional provisions; ask your lender.
The starting point: Rs. 14,723,446
In our step-by-step import duty example, a 2024 petrol hybrid with a 1,496cc engine and a CIF value of Rs. 4,800,000 reached a total landed cost of Rs. 14,723,446 after Customs Import Duty, Excise Duty, VAT, SSCL and the fixed levies. We will finance that amount.
All installments below use the reducing-balance method, which is how most Sri Lankan lenders calculate vehicle leases and loans, and they are calculated with the PiXAMP finance calculator.
The base case: 60% down, 14%, 5 years
- Down payment (60%): Rs. 8,834,067.60
- Amount financed (40%): Rs. 5,889,378.40
- Monthly installment: Rs. 137,035.53 for 60 months
- Total interest: Rs. 2,332,753.64
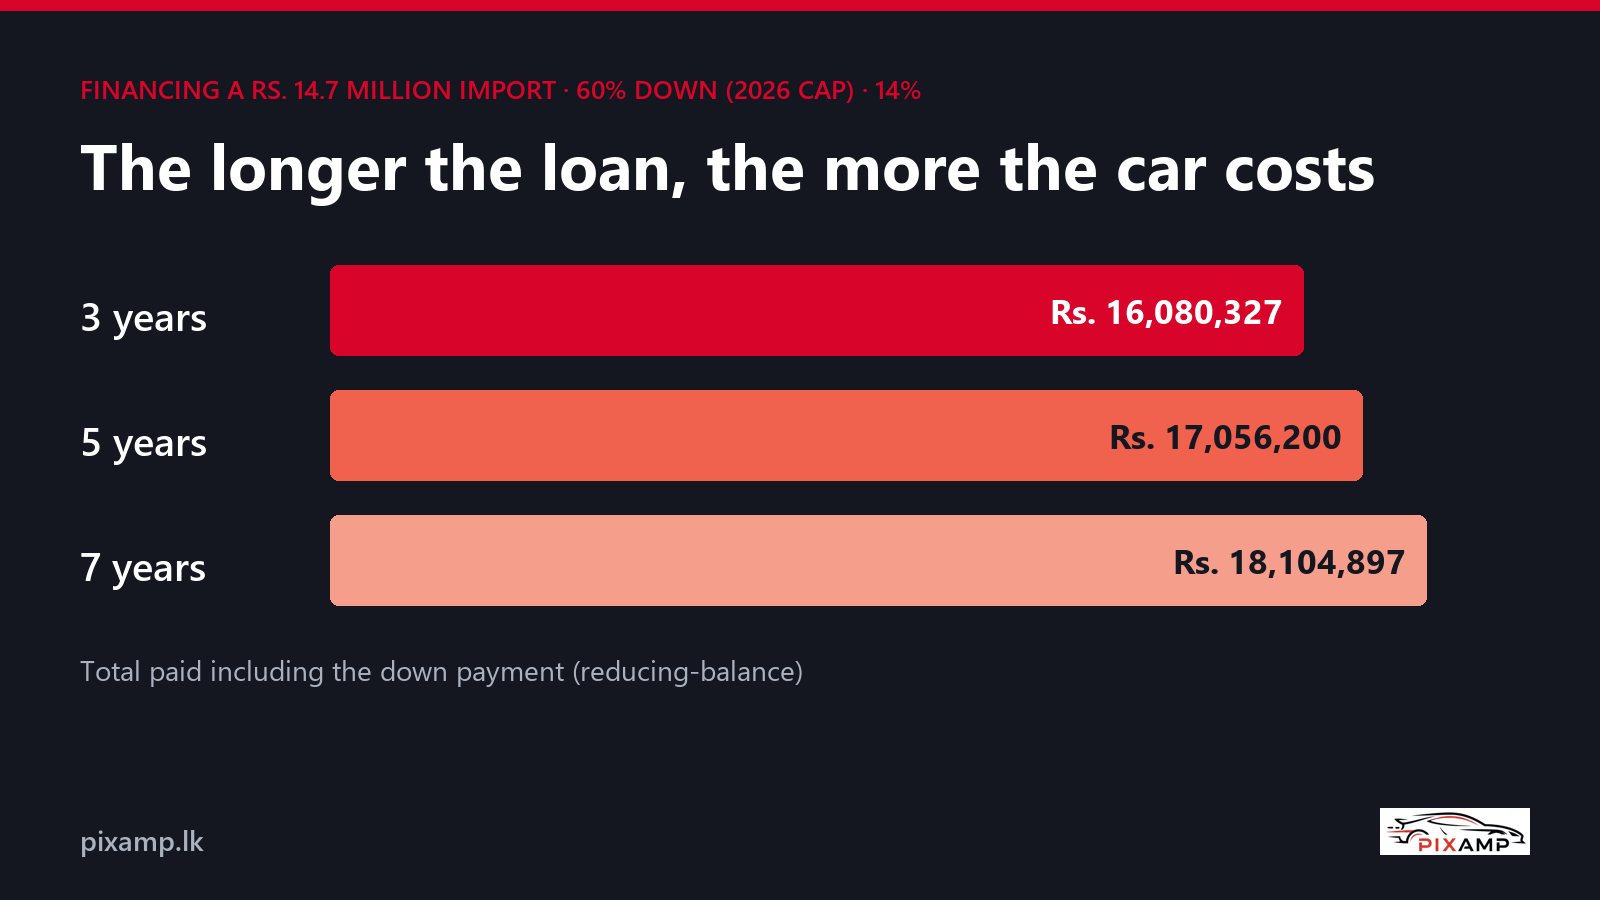
- Total paid, including the down payment: Rs. 17,056,199.64
Even at the maximum 40% financing, borrowing over five years at 14% adds about Rs. 2.3 million to the cost of the car.
Lever 1: the down payment
Keeping the rate (14%) and the term (5 years) the same:
| Down payment | Amount financed (Rs.) | Monthly installment (Rs.) | Total interest (Rs.) |
|---|---|---|---|
| 60% (the minimum for a new import) | 5,889,378.40 | 137,035.53 | 2,332,753.64 |
| 70% | 4,417,033.80 | 102,776.65 | 1,749,565.23 |
| 80% | 2,944,689.20 | 68,517.77 | 1,166,376.82 |
Moving from 60% to 80% down halves the installment, saving about Rs. 68,500 a month and about Rs. 1.17 million in interest.
Lever 2: the term
Keeping the down payment (60%) and the rate (14%) the same:
| Term | Monthly installment (Rs.) | Total interest (Rs.) |
|---|---|---|
| 3 years | 201,284.99 | 1,356,881.40 |
| 5 years | 137,035.53 | 2,332,753.64 |
| 7 years | 110,367.02 | 3,381,451.24 |
Stretching the loan from 5 to 7 years cuts the installment by about Rs. 26,700 a month, but adds more than Rs. 1 million of interest. A 3-year term saves almost Rs. 1 million of interest compared with 5 years, if you can manage the higher installment.
Lever 3: the interest rate
Keeping the down payment (60%) and the term (5 years) the same:
| Annual rate | Monthly installment (Rs.) | Total interest (Rs.) |
|---|---|---|
| 12% | 131,005.97 | 1,970,979.78 |
| 14% | 137,035.53 | 2,332,753.64 |
| 16% | 143,218.24 | 2,703,716.02 |
Each two percentage points of rate is worth about Rs. 6,000 a month, or roughly Rs. 360,000 to Rs. 370,000 over five years. Getting quotes from more than one bank or finance company is worth the effort.
The flat-rate trap
Some offers are quoted as a flat rate, which charges interest on the full amount financed for the whole term, even though you repay part of it every month. A flat rate looks much lower than a reducing-balance rate for the same cost.
For our Rs. 5,889,378.40 loan over 5 years:
- At 14% reducing balance, the installment is Rs. 137,035.53 and total interest is Rs. 2,332,753.64.
- At 14% flat, interest is 14% × Rs. 5,889,378.40 × 5 = Rs. 4,122,564.88, and the installment is Rs. 166,865.72.
The same headline rate costs nearly Rs. 1.8 million more when it is a flat rate. Always ask whether a quoted rate is flat or reducing balance, and compare offers on the same basis.
Costs the installment does not show
The installment covers the loan itself. Before you sign, also budget for:
- Fees: documentation, valuation and processing charges.
- Insurance: lenders usually require comprehensive insurance for the whole term.
- Early settlement charges, if you plan to pay off the balance early.
- Ownership: under a lease the finance company is normally the absolute owner until the final installment, and you are the registered owner.
Putting it together
For the same imported hybrid financed at the 40% maximum, the total you pay ranges from about Rs. 16.1 million (3 years at 14%) to more than Rs. 18.1 million (7 years at 14%), and more with a flat-rate offer. A few minutes with the numbers before visiting a lender can save more than the cost of a year’s fuel.
- Estimate the landed cost with the import tax calculator.
- Plan for a down payment of at least 60% on a new import, then try different terms and rates in the finance calculator.
- Ask each lender for the rate basis (flat or reducing), all fees and the early settlement terms, in writing.
Sources
- Central Bank of Sri Lanka, CBSL Act Directions No. 01 of 2026 (maximum loan-to-value ratios for motor vehicles, effective 25 May 2026), linked from the CBSL press release of 24 May 2026.
All figures are estimates for planning. Your actual installment depends on the rate, fees and conditions offered by your bank or finance company.